
Equipment purchase timing and tax planning for founder-led businesses
A machine, vehicle, or technology upgrade can solve a real operating problem. It can also tie up cash, create new payment obligations, and complicate a future sale. For founder-led businesses, the purchase date deserves more attention than a year-end reminder to buy something deductible.
Effective equipment purchase timing tax planning starts with the business case, then connects operating needs, cash availability, financing, and the tax rules that apply. A deduction may affect the economics, but it does not make an unnecessary purchase productive or an unaffordable purchase safe.
Keystone Consulting Team helps founders connect these decisions through fractional CFO services, active cash management, and proactive tax strategy coordinated with the owner's CPA. This article provides an educational framework for businesses across the United States. Confirm tax treatment with your CPA and legal questions with your attorney before acting.
Start With The Operating Need, Not The Deduction
Before choosing a purchase month, define what the equipment must accomplish. Is it replacing an unreliable asset, removing a production bottleneck, improving quality, or supporting work already under contract? Each reason creates a different urgency and a different standard for evaluating the expenditure.
A replacement that prevents recurring downtime may deserve priority over an expansion purchase based on uncertain demand. Conversely, replacing equipment simply because it is old may not be justified if maintenance costs remain manageable and performance meets customer requirements.
Write a short investment case that explains the problem, the alternatives, and the expected operating effect. Avoid treating projected revenue as certain. Distinguish work the company has already secured from opportunities that still depend on sales execution.
- Identify the specific operating constraint the equipment is expected to address.
- Compare purchase, repair, rental, outsourcing, and postponement where those alternatives are practical.
- Estimate the full cost of ownership, including installation, training, maintenance, and supporting infrastructure.
- Assign responsibility for measuring whether the equipment delivers the intended operating improvement.
This first step keeps tax considerations in their proper role. They inform a sound capital decision rather than substitute for one.
Separate Ordering, Payment, Delivery, And Placed-In-Service Dates
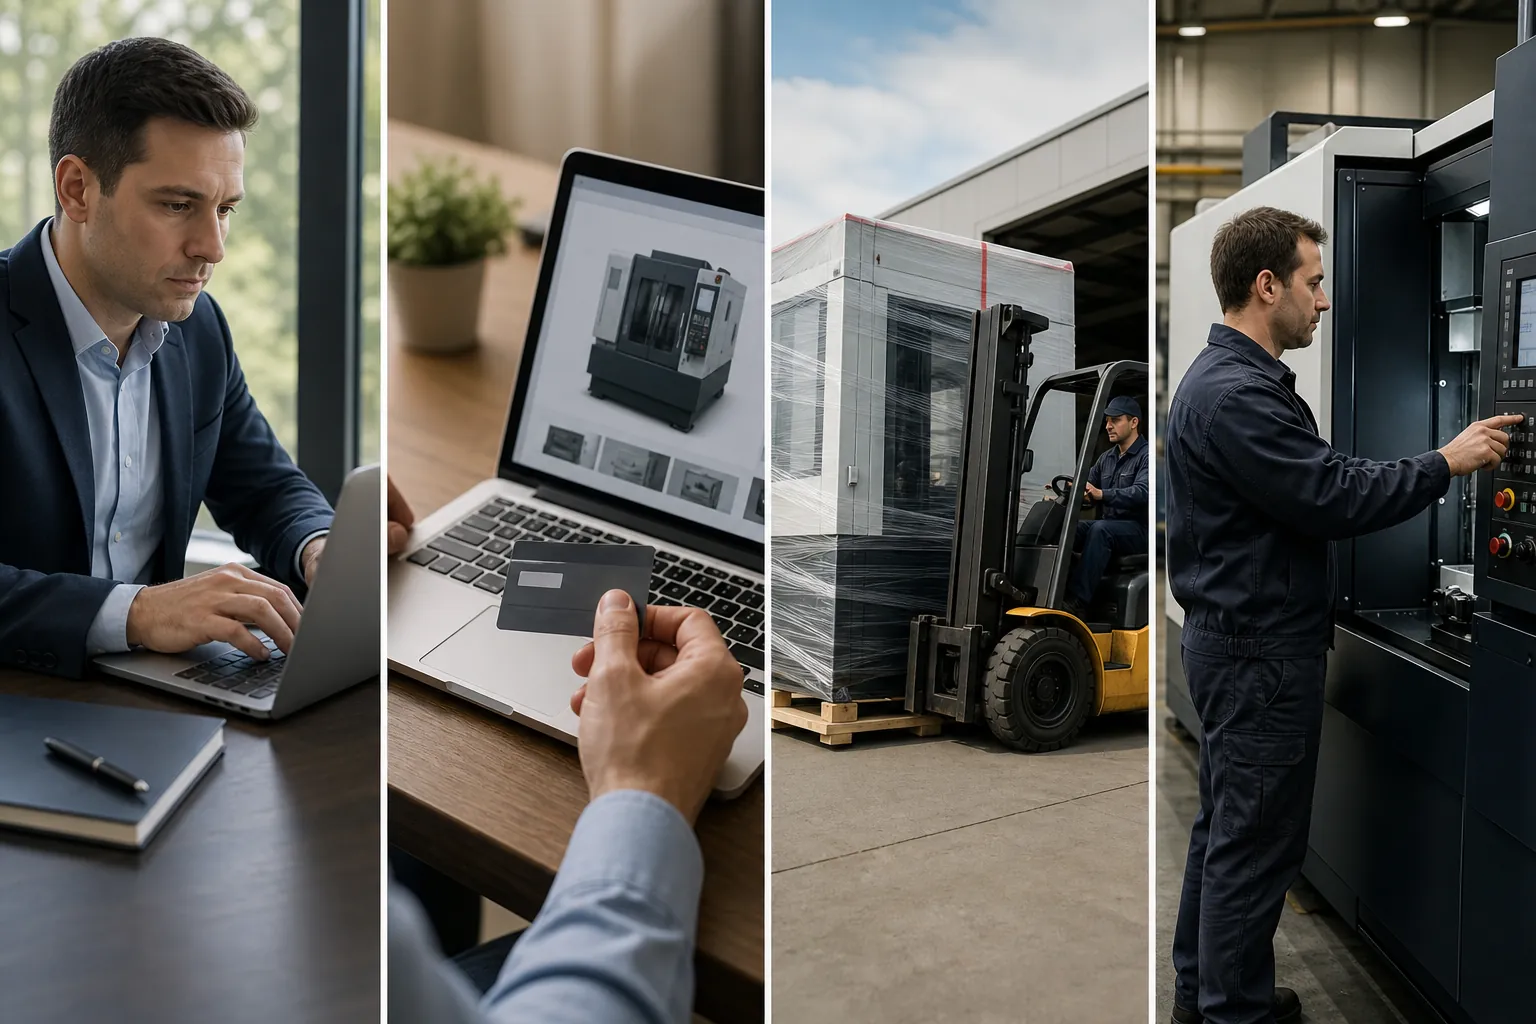
Equipment transactions often involve several dates: signing an agreement, paying a deposit, receiving delivery, completing installation, and beginning use. Those dates can fall in different tax years. Treating them as interchangeable can lead to incorrect expectations about deductions.
For depreciation purposes, placed-in-service status generally concerns whether an asset is ready and available for its specifically assigned function. Payment alone does not necessarily establish that status. Equipment sitting in a warehouse awaiting required installation may present a different situation from equipment that is ready for its intended use.
Your CPA should evaluate the facts and applicable rules. Accounting method, asset type, ownership arrangement, and the nature of the expenditure can all affect treatment. A deposit, prepaid expense, equipment purchase, and repair should not automatically be handled the same way.
Build a timeline with the vendor and operations team. Include site preparation, permits, electrical work, testing, software configuration, and employee training when relevant. Ask which steps are necessary before the asset can actually perform its intended function.
Keep contemporaneous records, such as delivery receipts, installation documents, acceptance records, and notes describing readiness for use. Good documentation supports accurate reporting and reduces the need to reconstruct events after year-end.
Ask Your CPA To Compare Tax Treatment Across Scenarios
Federal tax rules may allow different approaches to recovering equipment costs, including regular depreciation, Section 179 expensing, and bonus depreciation when applicable. Eligibility, limits, elections, and interactions require a current review. State treatment may differ from federal treatment.
Rather than asking only whether a purchase is deductible, ask your CPA to compare the relevant alternatives. A faster deduction is not automatically the best choice for every owner or entity. Its usefulness depends on the broader tax picture, including current income, expected future income, and restrictions that may apply.
Business-use requirements, taxable-income limitations, basis, at-risk rules, passive-activity rules, and other provisions may matter depending on the facts. Mixed personal and business use can introduce additional complications. Later changes in use or a disposition may also have tax consequences.
- Ask which cost-recovery methods are available for the specific asset and tax year.
- Ask how federal and relevant state treatment differ under each available approach.
- Ask whether limitations affect the timing or usability of a deduction.
- Ask how a future sale, trade-in, or change in business use could affect the analysis.
- Ask what elections and supporting records are needed before the return is filed.
Use those answers to compare buying now, buying later, or not buying. Keystone Consulting Team's proactive tax strategy is coordinated with the owner's CPA, keeping the operating decision and tax analysis connected without replacing the CPA's judgment.
Protect Liquidity Before Committing To Equipment
An equipment purchase can be reasonable over its useful life and still create a near-term cash problem. Deposits, freight, installation, and initial supplies may arrive before the equipment generates any operating benefit. Revenue growth can also require additional inventory and receivables funding.
Prepare a rolling cash forecast that includes those outflows alongside payroll, vendor payments, debt service, and estimated taxes. Model when cash leaves the business, not just when an expense appears in the financial statements. Include any temporary disruption during installation.
Separate expected tax effects from immediately available cash. A deduction is not a dollar-for-dollar reimbursement of the purchase price, and a projected tax benefit may not translate into cash when the vendor payment is due. Your CPA can explain the expected timing in your circumstances.
Stress-test the forecast against realistic setbacks. What happens if delivery is delayed, a major customer pays late, or the new equipment requires more training than expected? The goal is not to predict every problem. It is to understand how much flexibility the business retains.
Through active cash management, founders can establish liquidity guardrails before approving capital spending. Those guardrails should reflect the company's operating volatility and commitments rather than a generic reserve target.
Compare Cash, Financing, And Leasing On Total Economics
Paying cash may avoid financing costs, but it also reduces funds available for operations and other priorities. Financing can spread payments over time, while adding interest, fees, covenants, and potentially personal obligations. Leasing introduces its own contractual and tax questions.
Compare alternatives using the same operating assumptions and time horizon. Include down payments, periodic payments, fees, maintenance responsibilities, end-of-term obligations, and expected residual value where relevant. A low monthly payment can conceal a longer commitment or a significant final payment.
Do not assume that a contract labeled a lease receives a particular tax or accounting treatment. Your CPA should review classification, and your attorney should review legal obligations, especially guarantees, default terms, purchase options, and transfer restrictions.
- Match the payment schedule to realistic cash generation rather than optimistic sales targets.
- Check whether financing terms restrict distributions, additional borrowing, or other planned decisions.
- Understand what happens if the equipment becomes unsuitable before the agreement ends.
- Compare the effect of each option on liquidity under both expected and slower-growth conditions.
A capital allocation framework helps the founder evaluate these tradeoffs alongside other uses of cash. The right comparison includes what the business gives up by committing capital, not just whether a lender will approve the transaction.
Use Job-Level Profitability To Test The Business Case
For companies that perform distinct projects or jobs, equipment economics should connect to job-level profitability. A new asset may reduce labor hours, lower rework, improve scheduling, or allow work that previously had to be subcontracted. Those effects should be tested against actual operating data.
Start with a clear baseline. Review the jobs most likely to use the equipment and identify the costs that would actually change. Distinguish variable costs from expenses that remain even after the purchase. Faster production does not automatically eliminate payroll or overhead.
Capacity also needs context. If an asset creates more available production hours but demand does not fill them, the business may not realize the expected benefit. If another part of the workflow remains constrained, the equipment may shift the bottleneck rather than remove it.
Use conservative, expected, and stronger-demand scenarios. Include utilization, downtime, operator availability, maintenance, and any ramp-up period. Keep the assumptions visible so the team can update them as evidence changes.
After implementation, compare actual results with the original case. That review can improve future capital decisions even when the initial purchase does not perform exactly as expected. Fractional CFO services can help connect the operating assumptions to financial reporting and management decisions.
Consider Exit Readiness Before Making A Major Commitment
If a founder may sell the business in the coming years, equipment purchases deserve an additional review. Necessary reinvestment can support operational continuity, while unnecessary spending may consume cash without addressing what a buyer will examine.
Consider whether the purchase is maintenance capital expenditure or growth capital expenditure. Maintenance spending sustains the current business; growth spending aims to expand its capabilities. The distinction is useful, but it should be supported by facts rather than chosen to make the company look more attractive.
Buyers may examine asset condition, maintenance history, utilization, replacement requirements, and whether reported earnings rely on deferred investment. New equipment does not guarantee a higher valuation, and old equipment does not automatically make a business unmarketable.
Financing arrangements can also affect transaction preparation. Liens, payoff requirements, guarantees, and transfer restrictions may need attention before closing. The treatment of equipment-related debt and tax consequences will depend on deal structure and other facts.
As part of exit readiness and M&A preparation, organize the purchase rationale, asset records, financing documents, and maintenance history. Ask your CPA and attorney how the contemplated equipment decision might interact with a potential transaction. Avoid making a major commitment on assumptions about a future buyer's preferences.
Keep Financial Records Clean From Approval Through Disposal
Equipment planning is easier when the financial records tell a consistent story. Maintain a fixed-asset register with descriptions, acquisition costs, relevant dates, location, ownership information, and disposition details. Reconcile it with the general ledger and the CPA's depreciation records.
Invoices may include equipment, installation, service agreements, consumables, and training. Those components may require different treatment. Preserve itemized documentation and ask your CPA how costs should be classified rather than placing the entire invoice in one category by default.
Financial cleanliness metrics can help identify gaps that weaken decision-making. Useful checks include unreconciled asset balances, missing financing documents, unclear classifications, and assets that remain on the books after disposal. The purpose is reliable information, not cosmetic presentation.
- Record the approval rationale and the assumptions used to evaluate the purchase.
- Retain invoices and documents supporting the asset's readiness for its assigned use.
- Track debt balances and related obligations separately from the physical asset record.
- Document sales, trade-ins, retirements, and changes in business use promptly.
Consistent records support tax preparation, cash forecasting, and transaction diligence. They also help management see the cumulative impact of several smaller purchases that might otherwise escape meaningful review.
Connect Business Spending With The Owner's Broader Plan
Founders often make equipment decisions while also considering compensation, distributions, personal liquidity, and eventual ownership transition. A business purchase can affect all of those areas, even when it is operationally justified.
Business and personal wealth alignment means recognizing these connections before committing funds. The company may need cash for equipment at the same time the owner expects a distribution or has another personal funding need. Neither side of that equation should be treated as an afterthought.
Owner compensation structuring can also influence the broader planning discussion, but changes should not be made casually to accommodate a purchase. Entity type, tax rules, payroll requirements, and other circumstances can matter. Confirm proposed changes with your CPA and, where appropriate, your attorney.
Keep personal objectives visible without allowing them to obscure business performance. A clear discussion of competing cash needs helps the founder distinguish an attractive asset from a purchase that fits the current situation.
Build A Purchase Calendar That Supports Better Decisions
Start the process early enough to preserve choices. Identify likely equipment needs, gather vendor timelines, review cash forecasts, and schedule a CPA discussion before a deadline forces a rushed commitment. Revisit the calendar when operating conditions or tax assumptions change.
For each significant purchase, document the operating need, total cost, financing approach, expected readiness date, tax questions, and minimum liquidity requirements. Establish a final approval checkpoint before signing a binding agreement or making a nonrefundable payment.
The practical goal of equipment purchase timing tax planning is coordination. Operations should know when the asset is needed. Finance should understand how it will be funded. Your CPA should evaluate applicable tax treatment. Your attorney should address contract and legal questions where relevant.
Keystone Consulting Team brings those business considerations together through fractional CFO services, a capital allocation framework, active cash management, and exit readiness and M&A preparation. If you would like to discuss how an upcoming equipment purchase fits your company's financial priorities, call (815) 715-4884.
This content is educational only and does not provide specific tax, legal, or investment advice. Confirm the rules, documentation, and consequences that apply to your business with your CPA and attorney before making a purchase or election.
Call (815) 715-4884 to talk through next steps.