
What Should Founders Organize Before a Quality of Earnings Review?
A quality of earnings review can test whether a company’s reported performance is consistent, traceable, and clearly explained. Founders can prepare by organizing financial records, documenting unusual items, and addressing discrepancies before reviewers begin asking questions. The objective is not to present a flawless business. It is to make the company’s financial story easier to verify and understand.
Start With Reliable, Reconciled Financial Records
Begin with the core records that support the company’s reported results. Gather monthly profit and loss statements, balance sheets, cash flow statements, general ledgers, bank statements, and relevant account reconciliations for the periods likely to be reviewed. Confirm that reports use consistent accounting periods and that balances can be traced to supporting records.
Reviewers may compare the general ledger with bank activity, tax filings, payroll records, contracts, invoices, and management reports. Differences are not automatically problems, but unexplained differences can create delays. Identify where records rely on manual entries, spreadsheets, or estimates, then document the source and reasoning behind each material figure.
Financial cleanliness metrics can help founders assess whether accounts are current, reconciliations are complete, and reporting practices are applied consistently. Resolve stale balances, duplicate entries, misclassifications, and unsupported journal entries where appropriate. Keep a record of corrections so reviewers can follow what changed, when it changed, and why.
Build A Clear Monthly Earnings Bridge
A quality of earnings review typically focuses on how reported earnings were generated and whether the underlying activity appears repeatable. Prepare a monthly bridge that connects revenue, direct costs, operating expenses, and earnings to the company’s financial statements. Avoid presenting only annual totals, because monthly detail can reveal seasonality, customer timing, unusual expenses, or reporting inconsistencies.
Document the company’s revenue recognition practices, billing cycles, refund or credit activity, deferred revenue, accrued expenses, and other timing items. If policies changed, identify the date, business reason, and financial impact. The goal is to let a reviewer recreate management’s logic without relying on verbal explanations alone.
Founders should also compare internal management reporting with formal accounting records. If operational dashboards use different definitions, provide a reconciliation. Job-level profitability can be especially useful when project mix, labor deployment, or direct costs materially affect margins. Define how profitability is calculated and apply that method consistently across periods.
Document Adjustments Without Overstating Them
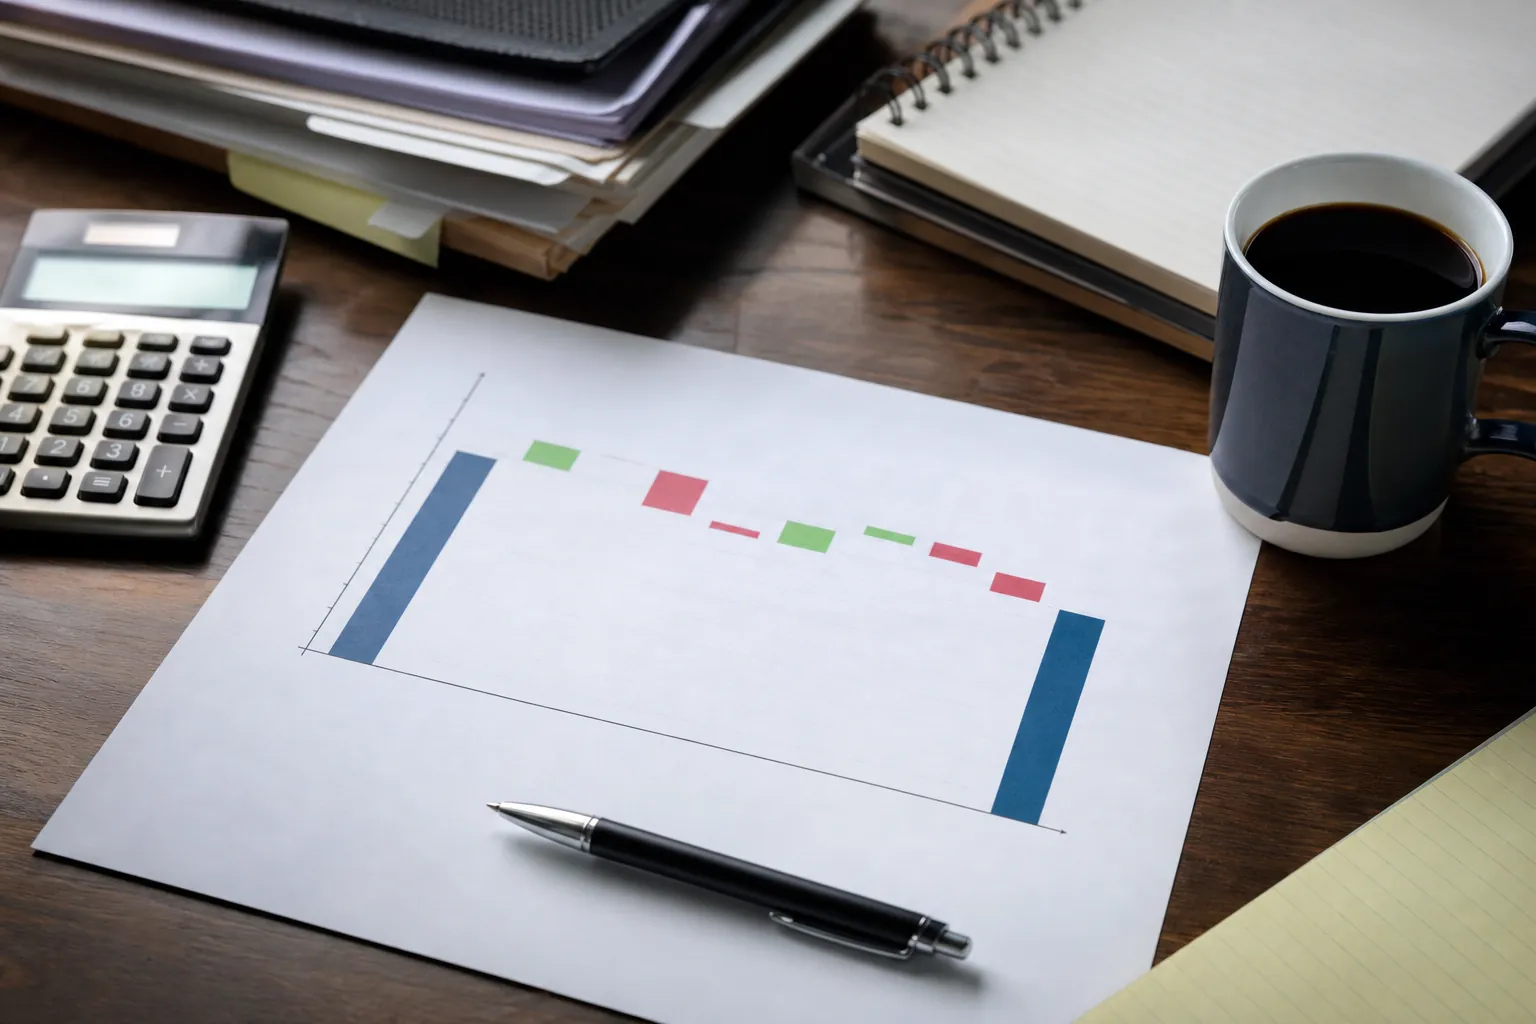
Founders often identify expenses or income they believe should be treated differently when evaluating ongoing performance. Examples may include owner-related items, one-time professional fees, discontinued activities, unusual repairs, or nonrecurring transaction costs. Prepare a schedule that lists each proposed adjustment, the relevant date, the general ledger account, the amount, and the supporting evidence.
Use neutral descriptions and avoid labeling an item “one-time” unless the facts support that conclusion. Reviewers may challenge adjustments that recur, lack documentation, or represent normal operating requirements. Maintain invoices, contracts, payroll detail, or other records that substantiate each entry.
- Separate proposed adjustments from reported accounting results.
- Explain the business purpose of each item.
- Show where every amount appears in the general ledger.
- Identify similar costs that occurred in other periods.
- Keep owner compensation and related-party activity clearly documented.
Owner compensation structuring may affect how stakeholders interpret expenses, but founders should confirm tax and legal specifics with their CPA and attorney before making changes.
Explain Revenue, Margins, And Working Capital
Prepare schedules that explain what drives revenue and gross margin. Depending on the company’s reporting structure, useful views may include revenue by month, customer, service category, project, or contract. Tie each schedule back to the financial statements and disclose any definitions, exclusions, or estimation methods.
Review changes in customer concentration, pricing, sales mix, direct labor, subcontractor use, and other cost drivers. Do not rely on a narrative that results “normalized” without showing the numbers. A concise variance analysis should identify what changed, the likely operational cause, and whether management expects the factor to continue. Present expectations as management assumptions, not guarantees.
Working capital deserves similar attention. Reconcile accounts receivable and accounts payable aging reports to the balance sheet. Review old receivables, customer credits, deposits, deferred revenue, accrued liabilities, and prepaid expenses. Active cash management records can provide context, but cash movement should not be confused with earnings. Keep separate explanations for profitability, working capital, and cash flow.
Prepare Management For An Efficient Review
Create a central request list with each document’s owner, reporting period, status, and location. Use consistent file names and preserve the original accounting exports. Assign one person to coordinate responses so explanations remain consistent and duplicate requests are minimized. If information is unavailable, say so directly and explain whether an alternative record exists.
Before diligence starts, conduct a question review with the people responsible for finance, sales, operations, and payroll. Confirm that they understand significant trends, accounting policy changes, customer issues, owner transactions, and major contracts. Written answers should be factual, concise, and supported by records.
Exit readiness and M&A preparation may also involve capital allocation, business and personal wealth alignment, and coordination among financial, tax, and legal advisers. Founders evaluating ongoing finance support can also read fractional CFO pricing for consulting firms. Keystone Consulting Team provides fractional CFO services and related financial preparation support. Educational information cannot replace transaction-specific guidance, so confirm accounting, tax, and legal decisions with your CPA and attorney.
Discuss Your Preparation Priorities
For a calm conversation about financial organization, exit readiness, or quality of earnings preparation, call Keystone Consulting Team at (815) 715-4884.
Call (815) 715-4884 to talk through next steps.