
Understanding rollover equity in a business sale
A business sale does not always end the founder’s ownership. In some transactions, the seller receives cash for part of the business and retains or acquires an equity interest in the company that owns it after closing. That continuing interest is commonly called rollover equity.
For founders across the United States, the decision is more complicated than choosing a cash percentage. Rollover equity connects today’s sale proceeds with future business performance, governance, financing, and a second potential liquidity event. Understanding those connections is essential before comparing offers.
This guide explains how a rollover equity business sale can work, what questions deserve attention, and how financial preparation supports a more informed decision. It is educational only. Transaction-specific tax, legal, and investment questions should be confirmed with your CPA, attorney, and appropriately qualified advisers.
What Rollover Equity Means In A Business Sale
Rollover equity generally means that a seller continues as an owner after selling the business. The structure might involve retaining shares, contributing existing ownership interests to a new entity, or reinvesting proceeds into the buyer’s ownership structure. These methods can have different legal and tax consequences.
The continuing investment may be in the operating company, a holding company, or a larger platform that owns several businesses. That distinction matters. A founder could move from owning one familiar business to holding a minority interest in an organization with other operations, expenses, and debt.
Buyers sometimes request rollover equity to align the seller with the business after closing. Sellers may view it as an opportunity to participate in future growth. Neither rationale establishes whether the arrangement is appropriate for a particular founder.
Rollover equity is also different from an earnout. An earnout is typically a contractual payment tied to defined outcomes. Equity is an ownership interest whose value and liquidity depend on the applicable rights and circumstances. A transaction can include both, but each needs separate analysis.
Separate The Purchase Price From Cash You Can Use
A headline purchase price is not the same as the cash available to the owner at closing. Debt repayment, transaction expenses, working capital adjustments, escrow amounts, and rollover commitments can change the amount that reaches the seller.
Start by distinguishing enterprise value from equity value. Enterprise value generally describes the value of business operations under the transaction’s assumptions. Equity value reflects the amount attributable to owners after the agreed treatment of debt, cash, and other adjustments. The purchase agreement controls the actual calculation.
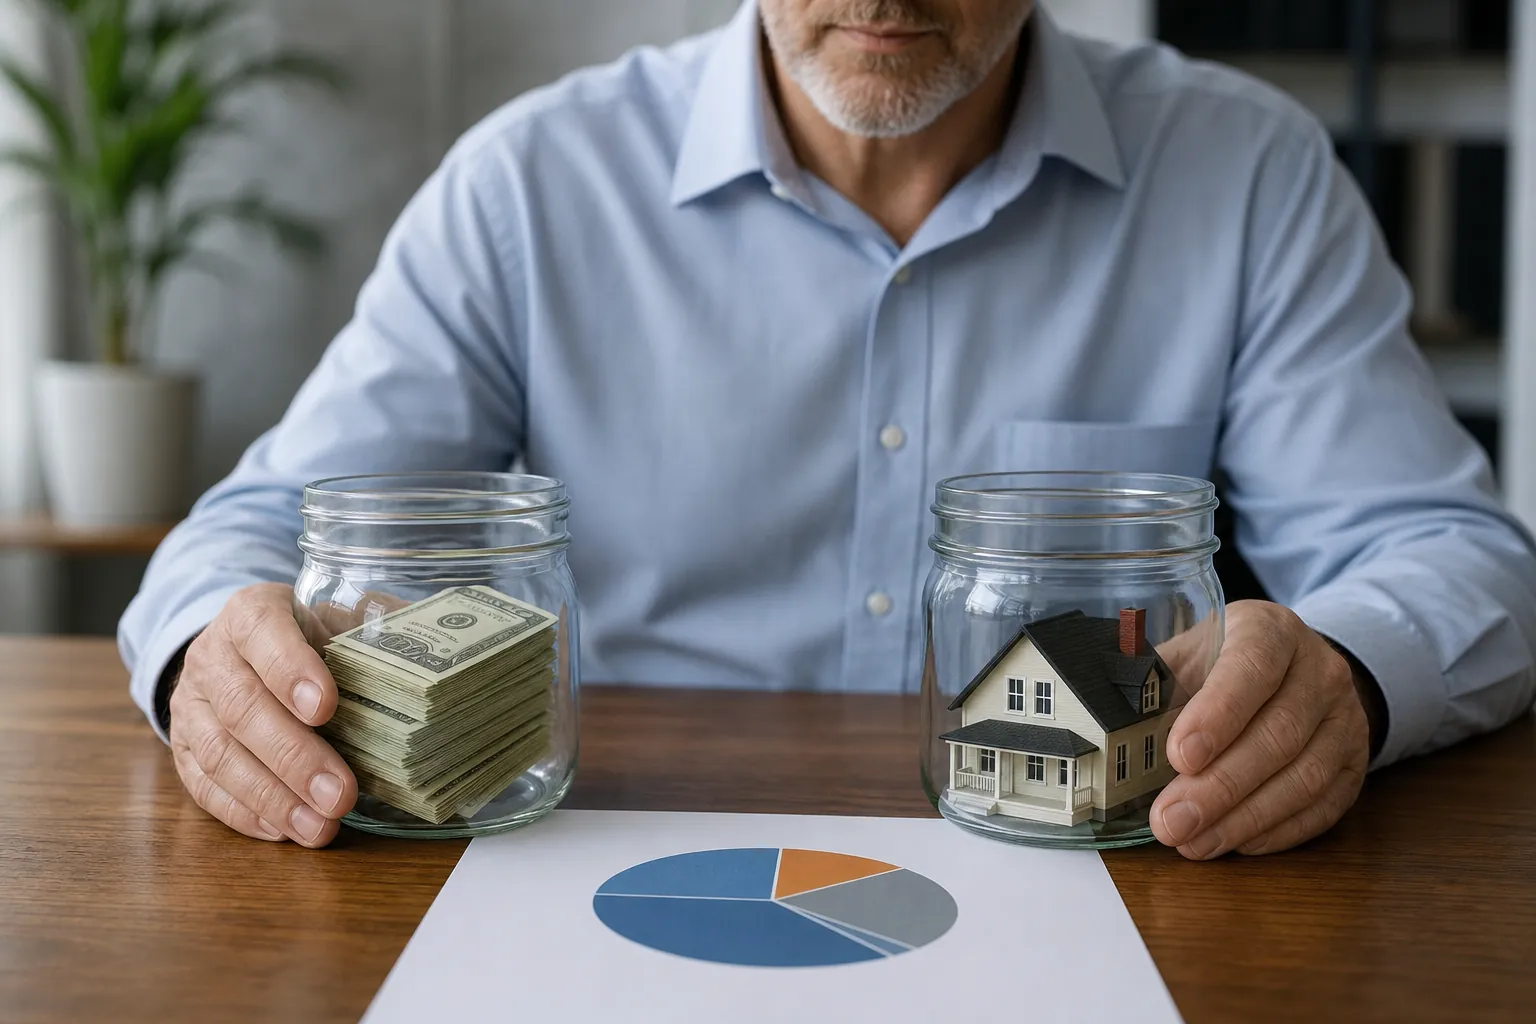
For illustration, suppose an offer includes $8 million in cash consideration and $2 million in rollover equity before expenses, taxes, or closing adjustments. That does not mean the founder receives $10 million in spendable funds. The rollover portion remains exposed to business risk and may be unavailable for years.
A clear proceeds schedule should separate the following items:
- Cash paid at closing should be distinguished from amounts held in escrow or subject to later adjustment.
- Rollover equity should be shown as a continuing investment rather than available cash.
- Debt repayment and transaction expenses should be identified using the agreement’s definitions.
- Contingent payments should be listed separately because their payment conditions may not be satisfied.
- Estimated tax obligations should be reviewed with the owner’s CPA rather than assumed from a headline price.
This schedule helps founders compare offers with different payment structures without treating uncertain or illiquid consideration as equivalent to cash.
Identify Exactly What You Will Own
A rollover percentage alone says little about the rights being purchased. A founder needs to understand the entity, equity class, valuation basis, and ownership percentage associated with the continuing investment.
Ask whether the founder and buyer are investing at the same implied valuation and holding securities with equivalent economic rights. Different equity classes can produce different outcomes even when both parties appear to own the same percentage.
The distribution waterfall deserves particular attention. It describes the order in which proceeds are allocated among investors. Preferred returns, liquidation preferences, management incentive interests, and other provisions may affect what a founder receives in a future sale.
A percentage can also change over time. Additional acquisitions, new investment, employee equity grants, or recapitalizations may dilute an existing interest. Dilution is not automatically harmful if the overall business becomes more valuable, but founders should understand the mechanisms and their possible effects.
- Ask which entity will issue the equity and what assets and liabilities it will own.
- Ask how the rollover investment’s value and the founder’s ownership percentage are calculated.
- Ask whether the equity carries preferences, restrictions, or obligations that differ from the buyer’s interest.
- Ask how future financing and incentive equity could affect the founder’s ownership.
- Ask your attorney to explain the distribution waterfall using several hypothetical exit outcomes.
Do not rely on a verbal description of equal treatment. The governing documents determine the rights.
Evaluate Liquidity And Personal Financial Exposure
Rollover equity is generally illiquid. A founder may be unable to sell it freely, borrow against it, or choose when to receive proceeds. Transfer restrictions and buyer approval requirements can limit available options.
A buyer’s expected holding period is not a guaranteed exit date. Market conditions, operating results, financing availability, and investor priorities can all affect the timing of a future sale. A business that performs well can still remain privately held longer than expected.
Consider how much of the owner’s total financial position would remain tied to the business after closing. A founder who has spent years concentrating wealth in one company may retain substantial concentration through the rollover, even after receiving meaningful cash proceeds.
Business and personal wealth alignment begins with identifying obligations that require dependable liquidity. Living expenses, planned purchases, family commitments, taxes, and other obligations should not depend on an assumed future equity sale.
Active cash management can help clarify which closing proceeds need to remain available and when. It does not remove rollover risk, but it separates near-term cash requirements from capital that may remain committed to the business.
The practical question is not simply whether the rollover might appreciate. It is whether the owner can tolerate uncertainty, illiquidity, and possible loss without undermining important personal objectives.
Understand Control After You Become A Minority Owner
Founders often focus on economics and underestimate the change in authority. After closing, the buyer may control budgets, hiring, acquisitions, financing, distributions, and the timing of a sale. Continuing to work in the business does not necessarily preserve ownership control.
Governance rights and employment responsibilities should be evaluated separately. An operating role may provide influence, but that influence can change if employment ends or leadership responsibilities shift.
Information rights matter because minority owners need visibility into performance. Discuss access to financial statements, budgets, debt information, and notices of significant events. Confirm how frequently information is provided and whether the governing documents support that access.
Your attorney should also explain provisions addressing transfers, forced sales, participation in sales, and repurchases. Common labels such as drag-along and tag-along do not replace a careful reading of the actual language.
- Clarify whether the founder receives a board seat, observer rights, or neither.
- Identify decisions that require investor consent and whether the founder has any consent rights.
- Determine what happens to equity if employment ends, including any repurchase triggers or pricing provisions.
- Review whether the documents permit additional capital requests and what happens if the founder does not participate.
- Understand how disputes, transfers, and a future sale are handled under the governing agreements.
These questions are not necessarily objections to a transaction. They make the ownership relationship more explicit before the founder commits.
Model Outcomes Without Treating Projections As Promises
A rollover decision should include several scenarios rather than one attractive growth forecast. The purpose is to understand exposure, not to predict a return.
A useful model connects operating performance, debt, future financing, ownership dilution, and the distribution waterfall. Strong revenue growth alone does not determine the founder’s proceeds. Cash conversion, financing costs, and investor preferences can materially change the result.
Include a downside scenario in which performance weakens or an exit is delayed. Include a scenario with moderate performance and a scenario with stronger results. Make the assumptions visible so advisers can challenge them.
For each scenario, distinguish the company’s value from the amount potentially distributable to the founder. An ownership percentage multiplied by a projected enterprise value may overlook debt and preferential distributions.
A capital allocation framework can organize this analysis around competing uses of funds, including reinvestment, debt reduction, acquisitions, and distributions. It can also reveal how the buyer’s priorities could affect liquidity for minority investors.
Scenario results are illustrations, not guarantees. They should not be presented as expected returns or used as a substitute for reviewing the legal rights attached to the investment.
Prepare Financial Information Before Negotiating
Financial preparation matters because rollover equity ties part of the seller’s outcome to the company’s continuing economics. A founder needs a credible understanding of earnings, cash flow, and operating risks before evaluating the buyer’s plans.
Fractional CFO services can help organize financial reporting and make assumptions easier to test. Exit readiness and M&A preparation can help owners identify inconsistencies and assemble information that supports a more coherent transaction discussion.
Financial cleanliness metrics should focus on whether the numbers are reliable and explainable. Relevant measures can include the timeliness of account reconciliations, unresolved balance sheet items, receivables aging, and consistency between management reports and accounting records.
Job-level profitability is particularly useful for businesses that deliver project-based work. It can show whether apparent growth produces durable margins or depends on jobs with weak economics. Accurate labor allocation, direct costs, and change-order tracking make the information more useful.
- Reconcile key accounts so historical financial statements have a dependable foundation.
- Document unusual expenses and owner-related items instead of assuming every adjustment will be accepted.
- Explain working capital seasonality so the closing mechanism reflects how the business operates.
- Review customer concentration and collection patterns to understand cash-flow vulnerability.
- Connect budgets to operating drivers so post-closing projections can be evaluated against realistic assumptions.
Better information does not guarantee a higher valuation or a successful sale. It helps founders and advisers distinguish supported conclusions from optimistic narratives.
Coordinate Tax Questions Before Signing
The word rollover does not mean a transaction is automatically tax-deferred. Tax treatment can depend on the entity types, transaction steps, equity received, and applicable federal and state rules.
A founder should involve their CPA and attorney before signing documents that establish the transaction structure. Waiting until closing can leave less opportunity to understand alternatives or resolve unexpected issues.
Proactive tax strategy, coordinated with the owner’s CPA, should address how the proposed structure interacts with the owner’s circumstances. That discussion may include the timing of taxable income, basis, reporting obligations, and the relationship between available cash and potential tax payments.
Future ownership can create additional tax questions. Depending on the structure, an owner may receive taxable allocations without matching cash distributions. Ask how tax distributions are addressed and whether the governing documents create enforceable obligations.
Owner compensation structuring also deserves separate attention when the founder remains employed. Salary, bonuses, employment terms, equity ownership, and transaction proceeds should not be treated as interchangeable. Confirm their treatment with the CPA and attorney.
No general article can establish the tax result for a specific transaction. Obtain a transaction-specific explanation before relying on any description of tax deferral or other tax treatment.
Compare Offers Using A Consistent Decision Framework
Two offers with similar headline values can expose a founder to very different risks. One may provide more immediate cash, while another may require a larger rollover into a more complex ownership structure.
A comparison should include cash certainty, financing conditions, closing adjustments, equity rights, employment obligations, and the quality of financial information available about the post-closing company.
Use a consistent set of questions:
- How much cash is expected at closing after identified deductions and estimated obligations?
- What portion of the founder’s wealth remains exposed to the post-closing business?
- What rights govern distributions, dilution, information access, and future liquidity?
- How much operating involvement is required, and does that fit the founder’s plans?
- What assumptions support the buyer’s business plan, and what happens if those assumptions fail?
- Which unresolved issues require clarification before the founder can make an informed decision?
The appropriate balance depends on the owner’s objectives and capacity to bear risk. There is no universal rollover percentage that works for every founder.
Bring The Financial Picture Into Focus
A rollover equity business sale combines an exit decision with a continuing ownership decision. Treating those as separate but connected choices makes it easier to evaluate immediate liquidity, future exposure, and the responsibilities that remain after closing.
Keystone Consulting Team supports founder-led businesses through fractional CFO services, exit readiness and M&A preparation, and business and personal wealth alignment. Financial preparation can help owners organize proceeds assumptions, understand operating drivers, and bring clearer questions to their CPA and attorney.
If you are considering a sale with rollover equity, call Keystone Consulting Team at (815) 715-4884 to discuss your financial readiness and planning priorities. Confirm all transaction-specific tax and legal details with your CPA and attorney before committing.
Call (815) 715-4884 to talk through next steps.